EV Industry Briefing: Batteries, Autonomous Driving and a Rapidly Changing Global Market
EV Industry Briefing: Batteries, Autonomous Driving and a Rapidly Changing Global Market
The electric-vehicle industry is entering a more complicated phase of growth. Battery technology is advancing, new models are arriving across several price segments, and manufacturers are expanding production capacity. At the same time, policy uncertainty, slowing consumer enthusiasm in some markets, supply-chain challenges and intense competition from China are reshaping the direction of the transition. The latest developments span everything from affordable city cars and long-delayed performance vehicles to grid-scale batteries and autonomous driving.
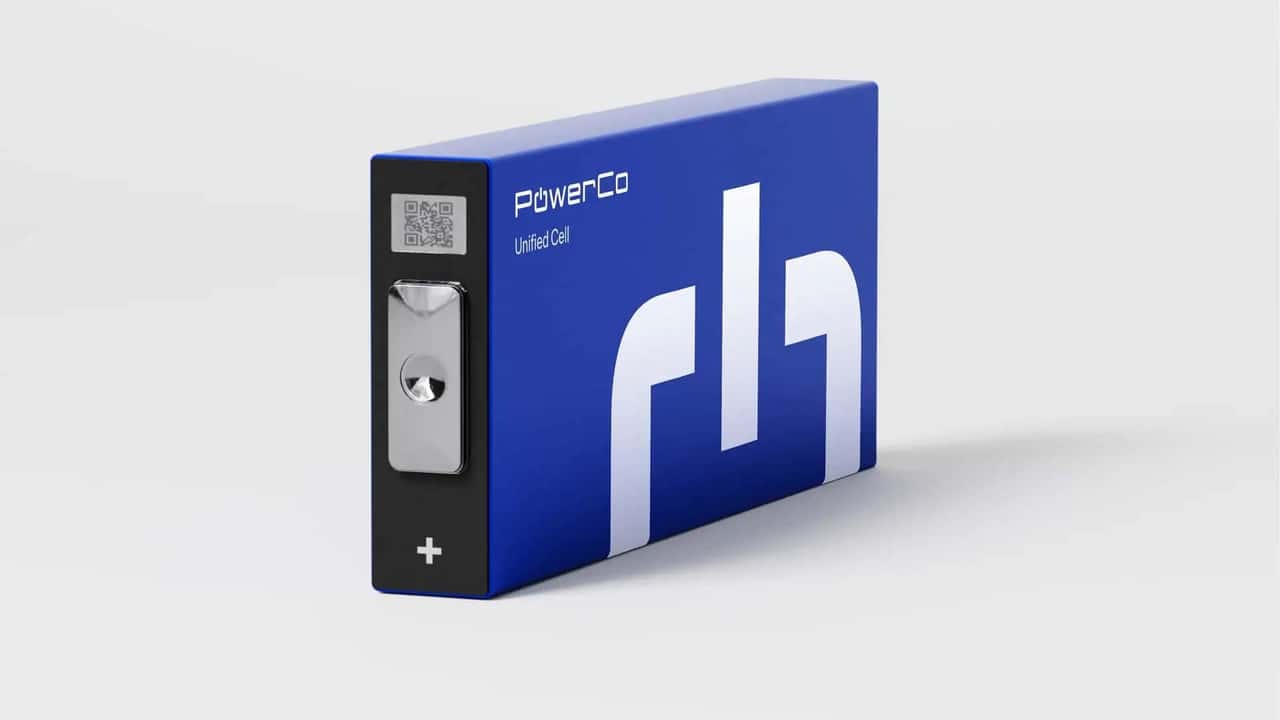
One of the clearest themes is the growing importance of lower-cost battery chemistry. Volkswagen has announced multiple arrangements with China’s Gotion to produce lithium-iron-phosphate, or LFP, batteries for mass-market electric vehicles. LFP cells generally offer lower costs, strong durability and improved resistance to thermal runaway, although they tend to provide less energy density than some nickel-based alternatives. Their increasing use suggests that automakers are prioritizing affordability and manufacturing scale as much as maximum driving range.
Solid-state batteries remain another major area of interest. BYD executive Stella Li said the company plans to have one model using solid-state batteries next year, while Hyundai’s research and development leadership expects small-volume vehicles with the technology to reach the market within five years. These batteries promise higher energy density, faster charging and improved safety, but the industry still faces difficult challenges related to production yields, materials, durability and cost. Early applications are therefore likely to be limited to premium or low-volume vehicles before the technology becomes widely available.
The competitive landscape is also being shaped by a wave of new and updated vehicles. The second-generation BYD Seagull, marketed in some regions as the Dolphin Surf, is expected to alter the assumptions surrounding affordable EV specifications. Its positioning reflects a broader trend in which compact electric cars are gaining better performance, more technology and greater practicality without moving entirely into premium pricing. Other updates are taking a more evolutionary approach, retaining an existing crossover’s basic platform while adding improved software, additional controls and upgraded equipment.
Several products illustrate how varied the market has become. The Chery Stockman combines two fuel tanks with a high-voltage battery, four-wheel drive and substantial towing capability, showing that electrification is not always limited to purely battery-powered vehicles. Meanwhile, the upcoming TZ will reportedly have less power than its Subaru counterpart, but is expected to reach the market sooner. In the luxury segment, the Genesis GV90 is being designed with unusual features such as a motorized display that rises from the dashboard, transforming the vehicle’s interior into a mobile entertainment space. Behind the novelty, however, engineers must solve complex problems involving packaging, reliability, software and user safety.
Performance and commercial vehicles are progressing as well. Tesla has delayed the reveal of its next-generation Roadster by two weeks because of weather concerns, extending an already lengthy wait for the high-performance model. More importantly for the industrial side of the business, volume production of the Tesla Semi has reportedly begun roughly a decade after its initial unveiling. The electric truck arrives at a time when fleet operators are paying closer attention to operating costs, charging infrastructure and regulatory pressure to reduce emissions. Its success will depend not only on range and power, but also on whether charging networks can support demanding long-haul and depot operations.
Battery manufacturing is expanding beyond vehicles. CATL supplied cells for what was described as the world’s first large-scale battery energy-storage project, and fourteen years later none of those cells has reportedly required replacement. That longevity is significant because stationary storage is becoming increasingly important as wind and solar power expand. Reliable batteries can help balance the grid, reduce peak demand and provide backup power, creating another large market for cell manufacturers and reinforcing the value of long service life.
The transition is nevertheless facing political resistance. U.S. regulators are attempting to slow the pace of the shift toward electric vehicles, while revised fuel-economy standards could create substantial public-health and environmental costs. The debate reflects a wider conflict between short-term consumer and industrial concerns and the longer-term consequences of continued dependence on combustion engines. Europe and China are continuing to develop EV policies, manufacturing capacity and charging infrastructure, meaning the global transition is unlikely to pause simply because the United States changes direction.
Consumer attitudes remain uneven. Political affiliation may be less important than expected when it comes to electric-vehicle buying intent, with Republicans and Democrats showing surprising similarities in some surveys. Age appears to be a more significant dividing line, with older consumers, particularly Baby Boomers, generally expressing less interest than younger buyers. This gap may narrow as prices fall, charging becomes more convenient and familiarity with EV ownership increases, but automakers still need to address concerns about range, resale value, repair costs and battery life.
The supply chain is another critical part of the story. MP Materials’ rare-earth magnet factory is approaching a milestone that could strengthen domestic production of components used in electric motors. Increasing local manufacturing would reduce dependence on overseas processing and help automakers manage geopolitical risk. However, new factories alone will not solve every vulnerability. The industry still needs dependable access to minerals, refining capacity, specialized equipment and skilled workers.
Autonomous driving is providing evidence of measurable progress, even as fully self-driving vehicles remain limited geographically. After 271 million driverless miles, Waymo reported that its vehicles were involved in 82% fewer injury-causing crashes than human drivers. Such statistics do not eliminate questions about edge cases, weather, regulation or public trust, but they indicate that automated systems may already offer safety advantages in carefully managed operating areas.
Taken together, these developments show an EV market moving beyond a simple story of replacing gasoline cars with battery-powered alternatives. The next phase will involve different battery chemistries, hybrid configurations, affordable compact vehicles, luxury technology, electric trucks, grid storage and autonomous services. Market share for EVs continues to rise while traditional combustion vehicles lose ground, but the path forward will not be uniform. Success will depend on reducing costs, building resilient supply chains, improving infrastructure and earning consumer confidence while governments decide how aggressively to support the transition.